A Property Can Be a Good Investment and Still Be a Bad Buy
The same property can be an excellent investment for one person and the wrong financial decision for another.
By Rennie Olajuyin
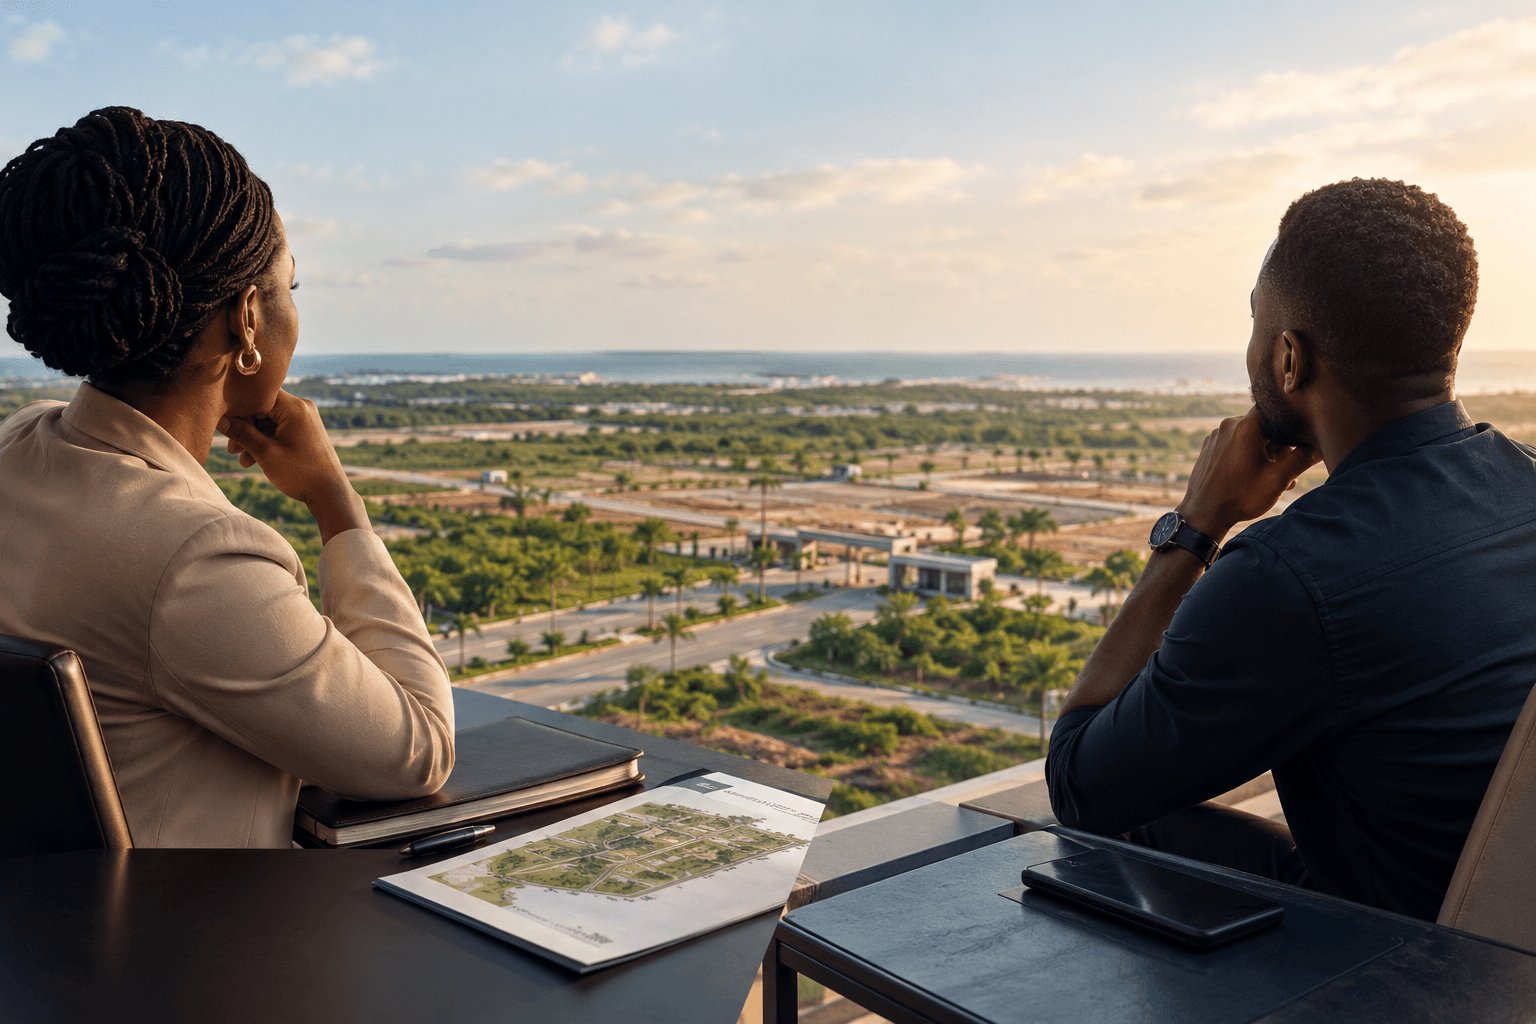
Mrs. M and Mr. A are looking at the exact same property.
Same estate. Same ₦50 million price tag. Same C of O. Same location in Ibeju-Lekki. Same proximity to the proposed Lekki International Airport.
Both have ₦50 million available.
Mrs. M buys.
Mr. A doesn’t.
Not because one of them knows something the other doesn’t. In fact, the property is objectively solid.
So why advise one to proceed while telling the other to stop and reflect?
Because a good property does not automatically make a good investment decision for every buyer.
The Financial Reality Behind The Decision.
Mrs. M is an experienced investor. The ₦50 million she is committing is a portion of a larger portfolio, reinvested profit from a previous transaction. She retains liquidity and other income-generating assets outside this purchase.
Mr. A is a first-time investor. That ₦50 million represents virtually his entire liquid net worth. After completing the transaction, he would be left with ₦100,000 in his account.
The property hasn’t changed, but the risk profile has.
For Mrs. M: The acquisition adds another growth asset to an already diversified portfolio.
For Mr. A: The acquisition concentrates nearly all of his available capital in a single, highly illiquid asset.
If Mrs. M encounters an unexpected capital need, she can draw from other resources.
If Mr. A needs cash six months after the purchase, his options are much more limited. He may have to try to liquidate the property - an asset that cannot always be sold quickly, or at the price he wants, simply because he suddenly need the money.
That is the difference between owning a good asset and taking an appropriate level of financial risk to own it.
Evaluating the Buyer, Not Just the Land
Property analysis often becomes overly simplistic because the industry evaluates the asset while ignoring the buyer.
Standard due diligence asks:
Is the location strategically sound?
Is the title secure and verifiable?
Is the price fair relative to market trends?
These are necessary questions, but they are only half of the equation.
The remaining questions should assess the impact of the purchase on the individual buyer:
What does this purchase do to your overall financial position?
What is your remaining liquid buffer after the purchase?
How much of your available capital will be tied up in this one asset?
Two buyers acquiring identical properties in the same estate can have vastly different levels of risk exposure simply because their financial positions are different.
Aligning the Asset With the Investment Objective
Financial risk is only part of the equation. The purpose of the investment matters too.
If Mrs. M is looking for long-term capital appreciation and can comfortably hold the property for seven to ten years, the asset may fit her objective.
If Mr. A needs immediate yield or ongoing cash flow, acquiring raw land or a long-term development asset may not serve that objective, regardless of how secure the documentation is or how much the location is expected to appreciate.
The fundamental question should therefore evolve from: “Is this a good property?”
to:
“Is this the right asset for what I am trying to achieve, given my current financial position?”
Objective metrics - title integrity, infrastructure, zoning, demand trends and exit potential- remain vital.
But they must be considered alongside personal liquidity, cash-flow requirements, holding capacity, investment horizon and risk tolerance.
The wisest real estate strategy isn’t always purchasing the maximum value you can afford.
It is ensuring that no single asset places unnecessary pressure on your financial stability.
Waiting is not necessarily missing an opportunity if it gives you the financial flexibility to buy later and comfortably hold the asset until its value fully matures.
At the end of the day, a property can be objectively good and still be the wrong purchase for you.
And sometimes, the most important thing to assess isn’t just the property.
It’s the person buying it.
Rennie's Insight
Don't evaluate a property in isolation. Evaluate the property and the financial position it leaves you in.
A ₦50 million acquisition can be a strong addition to an established portfolio, yet an unmanageable concentration of risk for a buyer committing all available reserves.
The core question isn’t just:
“Can I afford the purchase price?”
It is:
“What do my finances look like after the transaction closes?”
Rennie's Question
If the same property can be a great investment for one person and a risky decision for another, what is the single most important detail you would want to know about a buyer before recommending an asset to them?